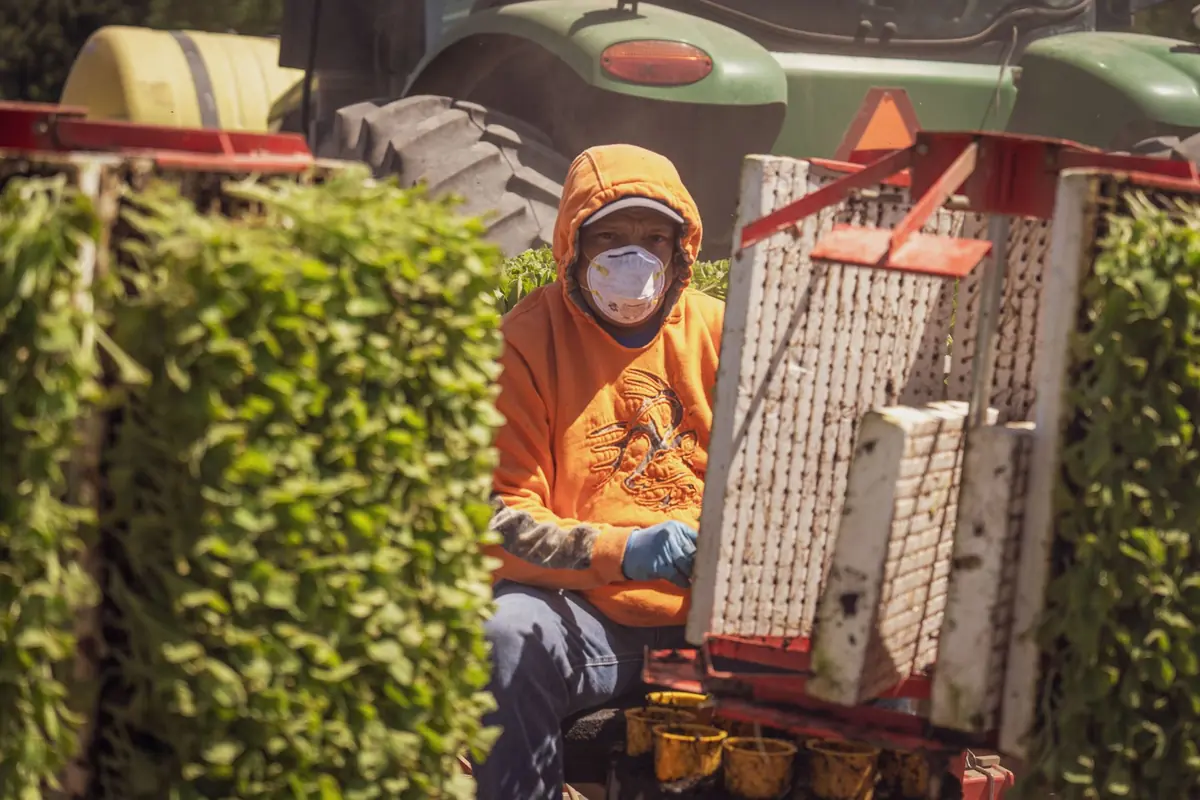
Health insurance for part-time & seasonal.
Seasonal roles almost never include benefits, and the coverage gap lands exactly when your income does. Enrolling any day of the year matters here.
- Pre-existing conditions covered
- Enroll any day of the year
- A licensed advisor, no pressure
- No cost to talk it through
Step 1 of 5
Let's find your coverage
Start with your state.
Plans from nationally recognized carriers
Carriers include UnitedHealthcare, Aetna, Cigna, Blue Cross Blue Shield, Humana, Anthem, Allstate Health, Oscar.
What a private PPO can do that most plans can't.
Pre-existing conditions covered
An advisor tells you straight which plans will take your health history.
Enroll any day of the year
No six-week window. Coverage can start when you need it to.
Broad nationwide PPO networks
Keep your own doctor in most cases and stay covered across state lines.
Never sold to third parties
Your details stay with us and are never resold.
What usually goes wrong
Seasonal work, year-round need for a doctor. Most people in your situation land on the marketplace, see an unsubsidized bronze premium around $750 a month with a deductible north of $5,000, and conclude that health coverage simply isn't affordable. That conclusion is often wrong — it's just that nobody showed you the other shelf.
Private PPO plans sit outside the marketplace. They're medically underwritten, which means not everyone is approved, and they aren't subsidized. What they offer in exchange is a materially lower premium, a broad nationwide network, and no enrollment window to wait for.
What a private PPO gives you
- Pre-existing conditions covered
- Enroll any day of the year — no six-week window
- Broad nationwide PPO networks
- Keep your own doctor in most cases
- Your details are never sold to third parties
And the honest caveat: if you qualify for Medicaid or a significant ACA subsidy, that will beat this. Your advisor will say so rather than sell around it.
Three things part-time & seasonal should check first.
- 01
No benefits at your hours
Part-time and seasonal roles rarely qualify for employer plans. Assume you need your own.
- 02
Coverage through the off-season
A plan that ends with the season leaves you exposed for months. Choose one that doesn't.
- 03
Medicaid and subsidies
Lower annual income may qualify you for Medicaid or a large subsidy. Check that first.
Straight answers for part-time & seasonal.
Could I qualify for Medicaid?
Possibly, depending on your state and annual income. If you do, it's often the best option, and an advisor will say so.
Is short-term coverage fine between seasons?
For a short, fixed gap, perhaps. For recurring seasonal work, ongoing coverage is usually safer.
Can I enroll when the season starts?
Private plans can start any time of year. Marketplace plans need open enrollment or a qualifying event.
Three steps, and you're never locked in.
- 01
Tell us the basics
State, household, pre-existing conditions and timing. About thirty seconds — no SSN, no date of birth.
- 02
A licensed advisor reaches out
Real options, real costs and the honest trade-offs, in plain English.
- 03
You decide
Enroll if it fits, or don't. No cost to talk and no obligation at any point.
See what you actually qualify for.
Four questions, a licensed advisor, a straight answer. No cost, no obligation, no pressure.
Secure & private. By submitting you agree to be contacted by a licensed advisor.
Year-round enrollment
Private PPO plans are not tied to open enrollment.
Never sold
Your details are not passed to a lead list.
256-bit SSL encrypted
Your details are protected from the first click.
No cost, no obligation
Talking it through is free. You decide.
Step 1 of 5
Let's find your coverage